

Market Update
September 2026 Market Review
Posted October 01, 2026
The month of August reminded many investors that the markets rarely move in a straight line. A combination of encouraging economic fundamentals, uncertainty in the bond market and renewed geopolitical turmoil led to increased volatility and shifting market leadership. But the underlying backdrop reinforced that the US economy continues to expand at a sustainable pace.
According to Raymond James Chief Investment Officer Larry Adam, “While higher interest rates and inflation concerns created bouts of volatility during the month, the fundamental backdrop remains supportive. Economic growth continues to exceed expectations, corporate earnings remain healthy and the consumer has shown remarkable resilience."
Consumer spending was essentially flat in real terms in July, while the labor market lost jobs for the first time since February. On the other hand, corporate investment remained consistent thanks to continued spending on AI infrastructure. Inflation, energy prices and geopolitical tensions once again joined forces to create headwinds as the Federal Reserve held interest rates steady, but under a watchful eye.
Equities saw a shift in leadership, with value-oriented sectors like health care, materials and energy outperforming as high-flying growth stocks consolidated. Corporate earnings growth was robust across a range of sectors, mirroring the broadening seen throughout the market.
Bonds provided solid returns as Treasury yields moved lower, led by declines at the longer end of the yield curve.
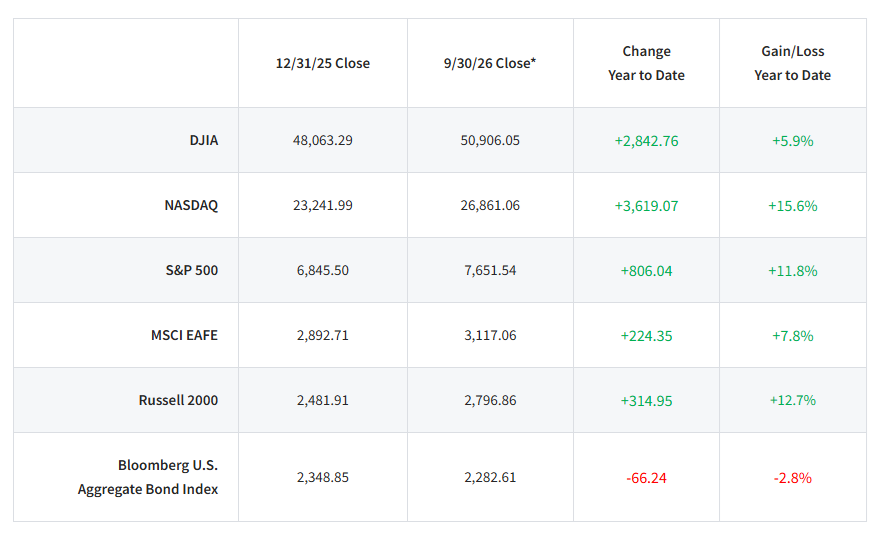
We’ll dive into more details below, but first, let’s look at how August finished.
*Data represents Sept. 30, 2026, closing values except for MSCI EAFE and Bloomberg Aggregate Bond indices, which represent Sept. 29, 2026, closing values.
Has jobs, lacks confidence
The August reports showed the job market remains healthy, with an estimated 162,000 jobs added and an unemployment rate of 4.1%. Hiring and separations also showed little movement during the month, pointing to continued stability in labor market turnover. The September preliminary Consumer Sentiment Index came in much weaker than expected, deteriorating significantly from August. Consumers’ concerns? Weak expectations for future business conditions, fuel prices and trade tensions.
Investors repositioning but staying invested
High oil prices and bond yields are both headwinds for equities, and absent the boom in AI capital expenditure, the headline indices would show this pressure more clearly. Investors rotated away from rate- and energy-sensitive stocks rather than retreating from the market – a sign of a healthy bull market. With the Fed’s rate hike, expect markets to be sensitive to inflation reports, job numbers and the price of debt.
Yields rise across the curve
Treasury yields rose broadly across maturities, with more concentration on the short end. Still, yields on the 10- and 30-year Treasuries reached multi-year highs. Investment-grade corporate debt rose roughly in tandem with Treasuries, keeping spreads flat, while municipal bond yields for AAA debt rose 50 to 85 basis points across the curve, pushing the 30-year AAA bond over 5% for the first time since 2011, and outpacing the rise of the Treasury yield. These moves increased the relative value of muni bonds to Treasuries from 70% to 77% for 10-year notes and 87% to 93% for 30-year bonds..
Middle East oil exports may be poised for partial recovery
Amid dual hurdles to Middle East oil exports – the restricted Strait of Hormuz and a damaged Saudi Arabian pipeline – there are tentative signs of progress at the end of September. Iran’s rhetoric about reopening Hormuz showed some softening, while the White House indicated its willingness to reengage with Iran diplomatically. Meanwhile, Saudi Arabia took steps to resume operations at the damaged pipeline, although supply recovery is unlikely to be smooth.
No breakdowns or breakthroughs at Trump-Xi meeting
The Trump-Xi meeting largely played out as expected, producing no major breakthroughs. More importantly, there were no breakdowns in the trade truce that has stabilized the bilateral relationship over the past year. The most impactful outcome was an agreement to extend the existing tariff and critical minerals truce (which was set to expire November 10) through January 10, while both sides agreed to continue economic negotiations, leaving the other issues around tariffs, technology, Taiwan and AI unresolved. The two countries are expected to have additional opportunities to engage around the November 18-19 APEC Summit and the December 14-15 G20 Summit. While tariff and trade risks remain, both governments appear to prefer managing those risks through recurring negotiations rather than returning to the escalation cycle seen previously.
US-Canada trade war accelerates
Trade negotiations between the US and Canada collapsed despite reportedly nearing an agreement that would have reduced steel and aluminum tariffs. Canada promptly imposed retaliatory tariffs of 15–50% on roughly $20 billion of US goods, while the Trump administration expanded its 50% Section 338 tariffs and announced targeted import bans. Although the dispute remains under negotiation, further escalations may precede real progress. By contrast, Mexico and the United States have accelerated bilateral discussions with the goal of reaching an interim agreement before the November 3 midterms, with Mexico reportedly seeking relief from US Section 232 tariffs while addressing US demands on automotive content and Chinese investment.
The bottom line
It’s rare for bonds to draw more attention than the equities market, so when it does happen, it’s easy to read an ill omen there. But while it’s true higher borrowing costs can drag at parts of the market, which we saw in the post-COVID inflation peak, the market and economy have remained resilient and investors are staying invested. Inflation, higher interest rates, energy prices, and geopolitics remain sources of uncertainty, but the underlying strength of the economy and corporate earnings continues to provide an important counterbalance.
Investing involves risk, and investors may incur a profit or a loss. All expressions of opinion reflect the judgment of the Raymond James Chief Investment Officer and are subject to change. There is no assurance the trends mentioned will continue or that the forecasts discussed will be realized. Past performance may not be indicative of future results. Economic and market conditions are subject to change. Diversification does not guarantee a profit nor protect against loss.
The Dow Jones Industrial Average is an unmanaged index of 30 widely held stocks. The NASDAQ Composite Index is an unmanaged index of all common stocks listed on the NASDAQ National Stock Market. The S&P 500 is an unmanaged index of 500 widely held stocks. The MSCI EAFE (Europe, Australasia and Far East) index is an unmanaged index that is generally considered representative of the international stock market. The Russell 2000 is an unmanaged index of small-cap securities. The Bloomberg Barclays US Aggregate Bond Index is a broad-based flagship benchmark that measures the investment grade, US dollar-denominated, fixed-rate taxable bond market. An investment cannot be made in these indexes. The performance mentioned does not include fees and charges, which would reduce an investor’s returns. Consumer Price Index (CPI) A consumer price index is a price index, the price of a weighted average market basket of consumer goods and services purchased by households. Consumer Sentiment is a consumer confidence index published monthly by the University of Michigan. The index is normalized to have a value of 100 in the first quarter of 1966.
Companies engaged in business related to a specific sector, including the technology sector, are subject to fierce competition and their products and services may be subject to rapid obsolescence. There are additional risks associated with investing in an individual sector, including limited diversification. Bond prices and yields are subject to change based upon market conditions and availability. If bonds are sold prior to maturity, you may receive more or less than your initial investment. Income from municipal bonds is not subject to federal income taxation; however, it may be subject to state and local taxes and, for certain investors, to the alternative minimum tax. Income from taxable municipal bonds is subject to federal income taxation, and it may be subject to state and local taxes.
Investing in oil or the energy sector involves special risks, including the potential adverse effects of state and federal regulation and may not be suitable for all investors. Investing in small-cap stocks generally involves greater risks, and therefore, may not be appropriate for every investor. The prices of small company stocks may be subject to more volatility than those of large company stocks. International investing involves additional risks such as currency fluctuations, differing financial accounting standards, and possible political and economic instability. These risks are greater in emerging markets.
Material created by Raymond James for use by its advisors.
